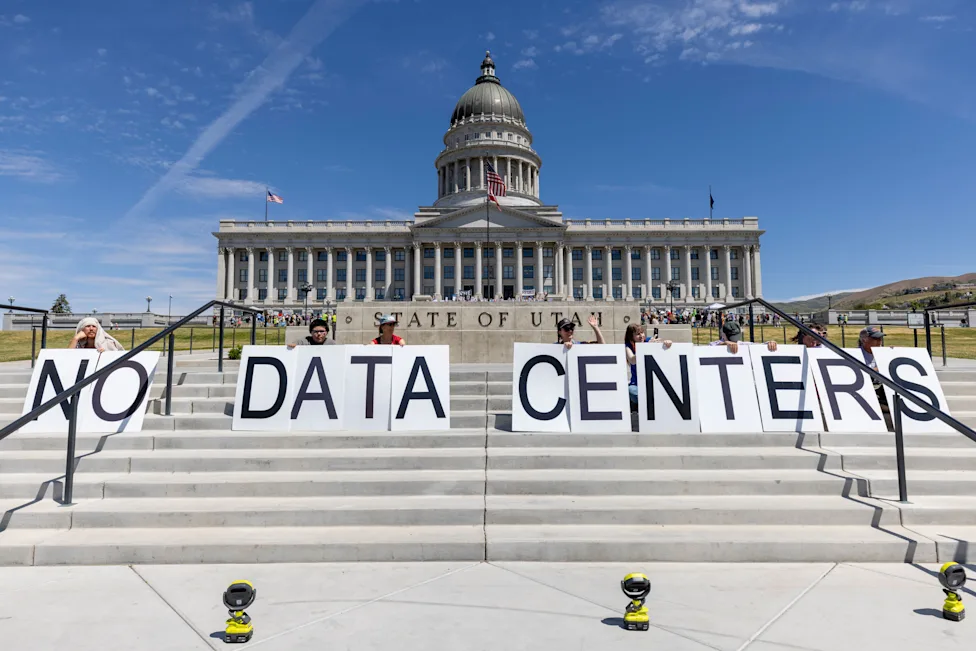
The four largest hyperscalers are on pace to spend roughly $725 billion on AI capital expenditure in 2026 — up 77% from about $410 billion in 2025. Analysts already expect that figure to top $1 trillion in 2027. To put that in perspective: this is the largest coordinated technology buildout in recorded history, and it is accelerating, not slowing down.
Understanding what is driving this spending, where the money is actually going, and whether it can be sustained is no longer a question only for investors and analysts. It matters for anyone building a business, evaluating technology partnerships, or simply trying to make sense of why AI has become the dominant story in global capital markets.
Who’s Spending What
According to capex tracking compiled by ValueAdd VC, the numbers are staggering even by Silicon Valley standards. Amazon leads among the big four at roughly $200 billion in projected AI infrastructure spending. Alphabet sits close behind at $195–205 billion after raising its spending ceiling at Q2 earnings. Microsoft follows at approximately $190 billion, and Meta rounds out the group at $125–145 billion after raising its own guidance twice in a single year.
Those four companies alone account for an extraordinary concentration of capital. But the picture gets even larger when you add Oracle’s own infrastructure buildout and the $500 billion Stargate project — a joint initiative involving OpenAI and SoftBank that is reshaping the AI compute landscape on its own. When you include Stargate and adjacent projects, total sector AI infrastructure spending in 2026 already exceeds $1 trillion. This is not a forecast or a projection. It is a commitment — in the form of announced budgets, signed contracts, and construction already underway.
Where the Money Actually Goes
The word “AI spending” can feel abstract. In practice, the overwhelming majority of this capital is going into a small number of physical and technological categories:
- Data centers — large-scale facilities requiring land, construction, cooling systems, and ongoing operational costs
- Nvidia GPUs and competing accelerator chips — the processors that actually run AI model training and inference at scale
- Custom silicon — proprietary chips developed in-house by Google, Amazon, Meta, and Microsoft to reduce dependence on any single supplier and improve efficiency
- Power infrastructure — increasingly the most consequential bottleneck in the entire buildout
That last category deserves particular attention. Microsoft’s projected electricity demand for AI data centers is expected to surge over 600% by 2030. That is not a typo. It reflects the enormous energy cost of running large language models at the scale these companies are planning for. The power constraint is real enough that Google spent $4.75 billion acquiring a power company outright, and Meta signed a major nuclear power purchase agreement. These are not minor operational decisions — they signal that securing reliable, clean energy has become a strategic priority on par with securing chip supply.
Meta’s Framing Is Deliberately Different From Its Metaverse Era
Of all the companies in this spending race, Meta occupies perhaps the most interesting position. CEO Mark Zuckerberg has explicitly framed this round of capital expenditure as a bet on “personal superintelligence” — a deliberate contrast with the metaverse narrative that defined Meta’s previous major investment cycle and drew significant skepticism from investors and the press.
The framing shift is not just rhetorical. It is tied directly to product. The launch of Meta’s Muse AI agent represents the kind of consumer-facing product this infrastructure spend is ultimately designed to support. Rather than asking investors to believe in a future virtual world, Zuckerberg is pointing to AI agents that interact with users today, with the argument that the infrastructure being built now will make those agents dramatically more capable over the next several years.
Whether that framing holds — and whether the AI agent use case proves as commercially durable as the social media products that made Meta what it is — remains an open question. But the contrast with the metaverse era is real, and it has meaningfully changed how Wall Street and the broader market receive Meta’s spending announcements.
Wall Street’s Growing Unease
It would be a mistake to read the scale of this spending as a signal of universal confidence. In fact, some of the most pointed skepticism is coming from within the financial community that has historically been most enthusiastic about big-tech growth stories.
Some analysts warn that free cash flow could fall by up to 90% across the largest hyperscalers in 2026 as capital expenditure dramatically outpaces revenue growth. The ratio of AI infrastructure spending to actual AI-generated revenue is a genuine and growing point of investor anxiety. Compute is being built at a pace that assumes demand will materialize on a timeline and at a scale that is, as yet, unproven.
Proponents of the spending argue that the history of transformative technology platforms — from mobile infrastructure to cloud computing — suggests that those who build ahead of demand are typically rewarded. Skeptics counter that those analogies have limits, and that the gap between today’s AI revenue and today’s AI capital expenditure is wider than at any comparable moment in the cloud era. Both positions have merit, and the honest answer is that this debate will not be resolved until the next two to three years of product revenue data come in.
The Global Picture Beyond the US
The spending race is not solely an American story. China’s total AI investment reached an estimated $125 billion in 2025 — substantial in absolute terms, though still well below the combined output of the US hyperscalers. The gap reflects both differences in private capital availability and the constraints placed on Chinese companies by US export controls on advanced semiconductors.
Gulf states are emerging as a third pole of AI infrastructure investment. Saudi Arabia has committed over $15 billion in new AI investments, and the UAE is actively constructing what it describes as the largest AI campus outside the United States. These are not symbolic gestures — they reflect a strategic calculation by resource-rich nations that AI infrastructure ownership is a form of geopolitical leverage, not just a technology investment.
For businesses evaluating their own AI infrastructure strategy, this global spending map carries practical implications. Regional compute capacity increasingly shapes where AI-dependent products can scale fastest, what latency users experience, and which regulatory environments govern the data being processed. Companies that factor geography into their AI infrastructure thinking today will likely have a meaningful advantage over those treating it as an afterthought.
Frequently Asked Questions
Is this spending level actually sustainable long-term?
That is the central debate on Wall Street right now. Proponents point to what they describe as insatiable compute demand — the argument that every new AI capability immediately generates new use cases that require more compute. Skeptics point to the widening gap between current capital expenditure and current AI-generated revenue, and question whether the productivity gains promised by AI will materialize quickly enough to justify the investment. There is no settled answer, and anyone who tells you otherwise is either speculating or selling something.
Which company is spending the most on AI infrastructure?
Among the big four hyperscalers, Amazon currently leads in absolute capex. However, all four companies have raised their spending guidance at least once in 2026, which signals that none of them view current expenditure levels as a ceiling. The more meaningful question may not be who is spending the most today, but whose infrastructure investments translate most efficiently into profitable AI products over the next several years.
The Bottom Line
What began as a competitive race between a handful of ambitious technology companies has become the defining capital allocation story of the decade. The consequences extend well beyond stock prices and quarterly earnings calls. Power grids in multiple countries are being redesigned around AI data center demand. Global chip supply chains are under sustained pressure. Entire regions are reconfiguring their economic development strategies around the question of where AI compute will be located.
The companies that will ultimately benefit most from this buildout are not necessarily the ones spending the most today — they are the ones that convert this infrastructure into AI products that generate durable, scalable revenue. That challenge, more than the spending itself, is what the next chapter of this story will be about.